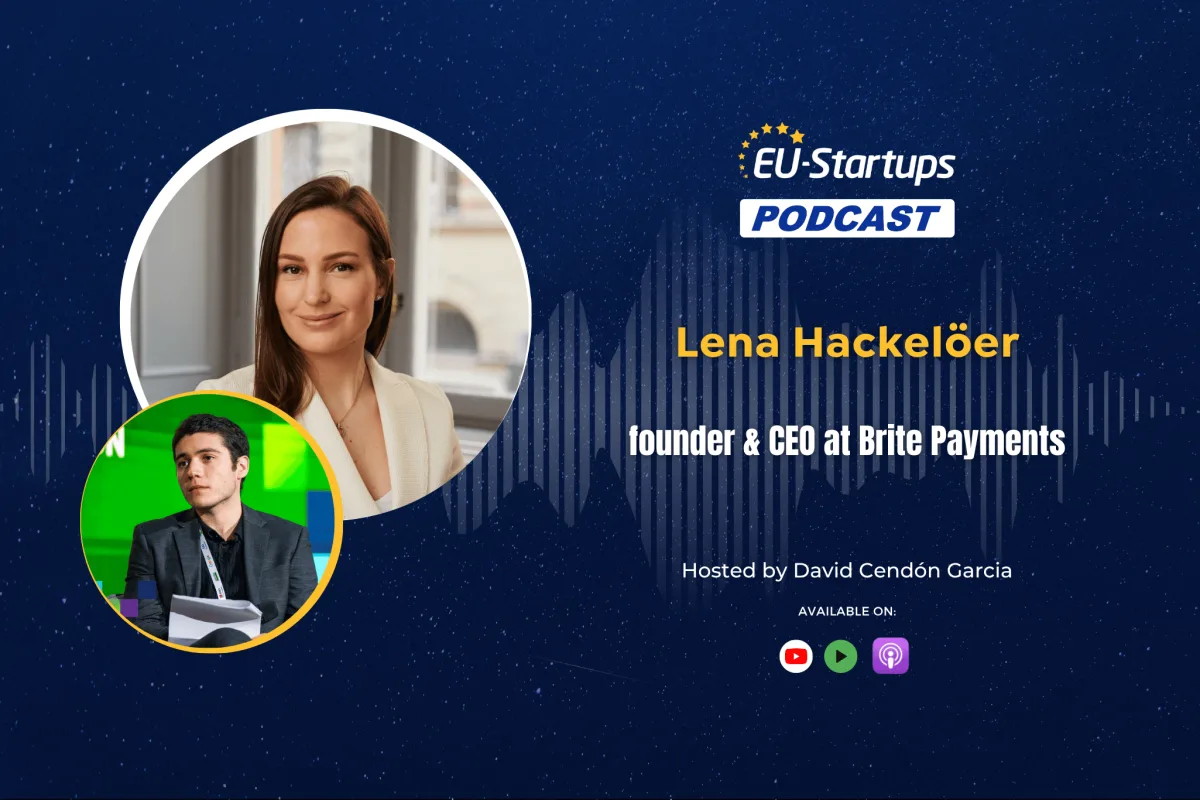
Lena Hackelöer, founder and CEO of Brite Payments, recently sat down to discuss her company's trajectory, the evolving landscape of European payments infrastructure, and obstacles that confront founders building fintech across the continent.
Since its founding in Sweden in 2019, Brite has transformed into a major pay-by-bank operator with a presence spanning 27 European markets. The company's expansion into Germany and France followed its Series A funding round.
Hackelöer's path to founding Brite was shaped by two distinct phases of her career. Her time at Klarna during its explosive growth phase provided crucial lessons in building and scaling a fintech business internationally, while a subsequent position at a publicly listed financial services firm gave her exposure to navigating heavily regulated sectors.
Sovereignty and Market Adoption
A central focus of the discussion was European payment sovereignty. Brite is constructing a continent-wide instant payment network designed to decrease dependence on infrastructure controlled by non-European entities. Yet Hackelöer emphasizes that sovereignty as a concept alone will not guarantee market traction. Instead, merchants and consumers make decisions based on what serves them best: ease of use, dependability, conversion performance, and cost efficiency.
The Complexity of European Expansion
Scaling payment solutions across Europe presents distinct challenges that cannot be overlooked. The continent's diversity—spanning languages, customs, banking infrastructure, regulatory frameworks, and how people actually behave as consumers—means treating Europe as a unified market is unrealistic. While EU passporting rules allow licenses to function across member states, individual regulators frequently impose their own specific demands.
This reality has shaped Brite's operational model. The company maintains a unified technology foundation while embedding local teams who understand each market's nuances. Consumer preferences vary significantly: German users tend to prioritize security and privacy protections, whereas Swedish consumers demonstrate greater acceptance of digital openness. Brite tailors its approach accordingly.
What Drives Adoption of Pay-by-Bank
Looking at the future, Hackelöer identifies convenience as the primary force behind pay-by-bank growth. Advances in mobile banking capabilities, authentication between applications, and real-time payment processing are making transactions quicker and smoother. These improvements enable immediate transaction confirmation, faster refund processing, and accelerated fund settlement.
Women in FinTech: Progress and Persistent Gaps
The conversation also addressed female entrepreneurship and visibility within the fintech sector. Hackelöer observes that advancement is occurring as more women accumulate senior-level experience and expand their professional networks. Nevertheless, structural obstacles remain entrenched: disparities in venture funding, restricted pathways into technical roles, and underrepresentation of women in engineering positions all continue to hinder progress.
Key Takeaways
- Brite Payments has evolved from a 2019 Swedish startup into a leading pay-by-bank platform active in 27 European markets.
- Hackelöer's background at Klarna during rapid expansion and subsequent work in regulated finance both informed her founding strategy.
- While European payment sovereignty carries importance, market adoption ultimately hinges on convenience, reliability, conversion performance, and commercial benefits.
- Europe's regulatory fragmentation, varied banking systems, and diverse consumer preferences require localized strategies despite unified technology platforms.
- Technological improvements in mobile banking, instant payments, and app-to-app authentication are accelerating pay-by-bank adoption.
- Advancing female representation in fintech demands expanded access to capital, more opportunities in technical fields, and greater women in senior engineering roles.
Source: EU-Startups